Research Note / Market Structure
Prime Brokerage and Clearing Rails for Emerging Quant Managers
A short primer on quantitative prime brokerage: custody, clearing, margin and multi-account execution, and the questions allocators should ask.
- Mandate focus
- Prime brokerage, clearing and custody rails
- Audience
- Emerging managers, allocators, operations teams
For an emerging quantitative manager, quantitative prime brokerage is the plumbing that decides whether a good strategy can be run in practice: where assets are held, how orders reach the market, how margin is managed and how allocators see what is happening. This short primer explains the main pieces, compares the two common ways of organising them, and lists the questions an allocator should ask about the clearing rails behind a program. It is educational, written for professional investors, and is not an offer or solicitation.
1. What Prime Brokerage Covers for a Quant Manager
A prime broker typically combines custody, clearing, access to execution venues, margin and reporting in one relationship. For a systematic manager each of those has a practical consequence. Custody determines who can move cash. Clearing and venue access determine which markets the strategy can trade and at what cost. Margin rules cap the leverage the strategy can really use. Reporting is what an allocator checks against the manager's own figures.
The broker is also the party that matters when something goes wrong. Counterparty risk includes operational or financial distress at prime brokers and custodians, which is why an allocator should know exactly which institution holds the assets. Qlumina's published research names Clear Street and Britannia as prime brokers on its rails.
2. The Emerging Manager's Problem
Traditional prime brokerage relationships have historically screened on size, and assembling execution, risk and reporting tooling is a cost a new firm carries before it has raised capital. That is part of the launch barrier described in The Emerging Quant Spin-Out Dilemma.
Running on a platform that already has the broker relationships, execution routing and risk controls in place changes the question. Instead of asking whether a manager can build the infrastructure, an allocator can ask whether the manager has a strategy that survives the review. Managers can see how that works on the portfolio managers page.
3. Two Ways to Organise the Rails: Pooled Fund or SMA
Capital can reach a manager's strategy through a pooled fund vehicle or through separately managed accounts at the allocator's own broker. Neither is universally better. A pooled vehicle can suit infrastructure-intensive strategies, scale economies and netting, while an SMA gives the allocator direct ownership and visibility.
| Dimension | Pooled fund vehicle | Separately managed account |
|---|---|---|
| Where assets sit | In a fund vehicle that owns the underlying positions | In a segregated account in the investor's own name, with no commingling |
| Manager authority | Set by the fund's constitutional documents | Trading only, through a limited power of attorney |
| Visibility | Periodic reporting, monthly or quarterly | Real-time broker access around the clock, plus daily statements |
| Liquidity | Subject to notice, with possible lock-ups and gates | Positions can be liquidated or the mandate ended on any business day |
| Netting and margin | Cross-strategy netting inside one vehicle can reduce collateral needs | Separate accounts can require more aggregate collateral |
The investor guide covers when each structure fits and where every fee sits. The structural argument is developed in The Death of the Cayman Master-Feeder, and the full comparison lives in the investor guide.
4. How One Strategy Reaches Many Accounts
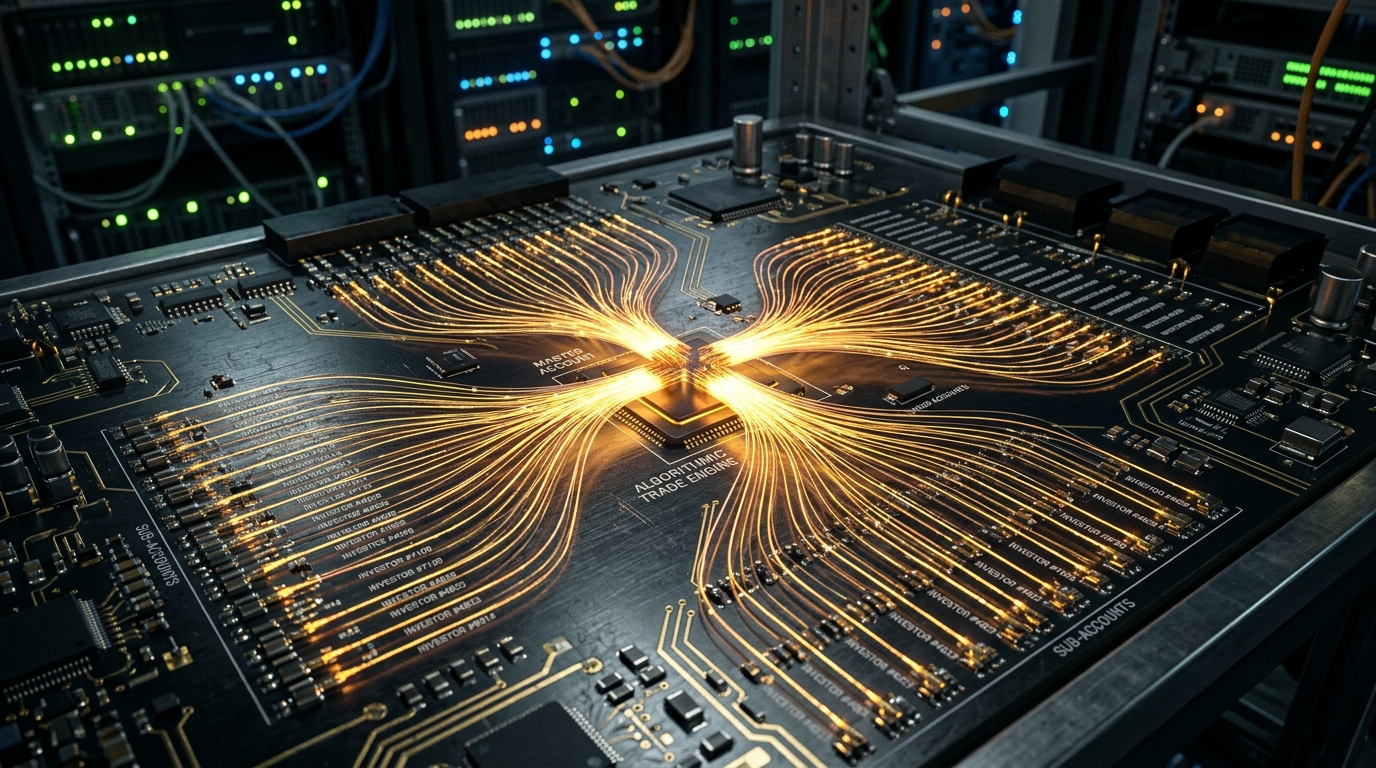
With SMA rails, the same strategy has to be delivered into many separate accounts without any one of them being disadvantaged. In practice that means a single definition of the strategy, with each account's mandate applied on top, and orders routed to each account's broker with venue-specific handling.
- Proportional sizing: child orders are generated in proportion to each account's net equity and rounded down to whole lots, so no account holds a fraction of a contract that cannot exist.
- Partial fills: when a broker returns a partial fill, the allocation across accounts has to be rule-based, otherwise performance disperses between accounts for reasons unrelated to the strategy.
- Continuous reconciliation: positions, cash and weights are reconciled across accounts so a break is found by the system before the allocator finds it on a statement.
The mechanics of replication are set out in Institutional Trade Replication and Sub-Account SMAs.
5. Margin and Broker-Level Controls
Leverage is not a free parameter. For futures, exchanges require margin that is recalculated against stressed scenarios, so a strategy needs collateral beyond the minimum to avoid forced liquidation during large moves. Minimums reflect this: indicative SMA minimums for CME global futures programs run from $500K to $2M+, because discrete contract sizing across a multi-asset book needs capital to support it. The detail is in CTA and Systematic Managed Futures.
6. Five Questions About the Clearing Rails
Before committing capital to any systematic program, ask the manager and the broker these questions and expect specific answers:
Allocators comparing programs can browse them on the Apex Marketplace or in the program catalogue. To see how evidence is examined before a program is shown, read what a verified quant track record means and how the allocator network works.
The Rails Decide Who Controls the Cash
Prime brokerage is easy to treat as back-office detail, but it determines who holds assets, how orders are allocated, how margin is managed and what an allocator can verify independently. Qlumina is not a prime broker and does not take custody of funds; it acts as investment manager under a limited power of attorney.
Investing involves substantial risk of loss. The value of investments and the income derived from them can fall as well as rise, and investors may not recover the amount originally invested. Past performance is no guarantee of future returns. This note is for professional investors only and is not financial, legal, tax or investment advice. See the risk disclosure.
Manager Onboarding
Qualify a Strategy and Run It on Alpha OS
Systematic managers can apply to run on the platform through a quantitative review, an operational review and a live pilot allocation.
Research notes are published for professional readers. Not an offer or solicitation. Risk disclosure