Research Note / Operating Platforms
Hedge Fund in a Box: What the Term Means and What It Does Not
Hedge fund in a box explained: the six functions an emerging manager must stand up, what a platform can and cannot replace, and how to evaluate one.
- Focus
- Hedge fund in a box
- Audience
- Professional investors, allocators, family offices
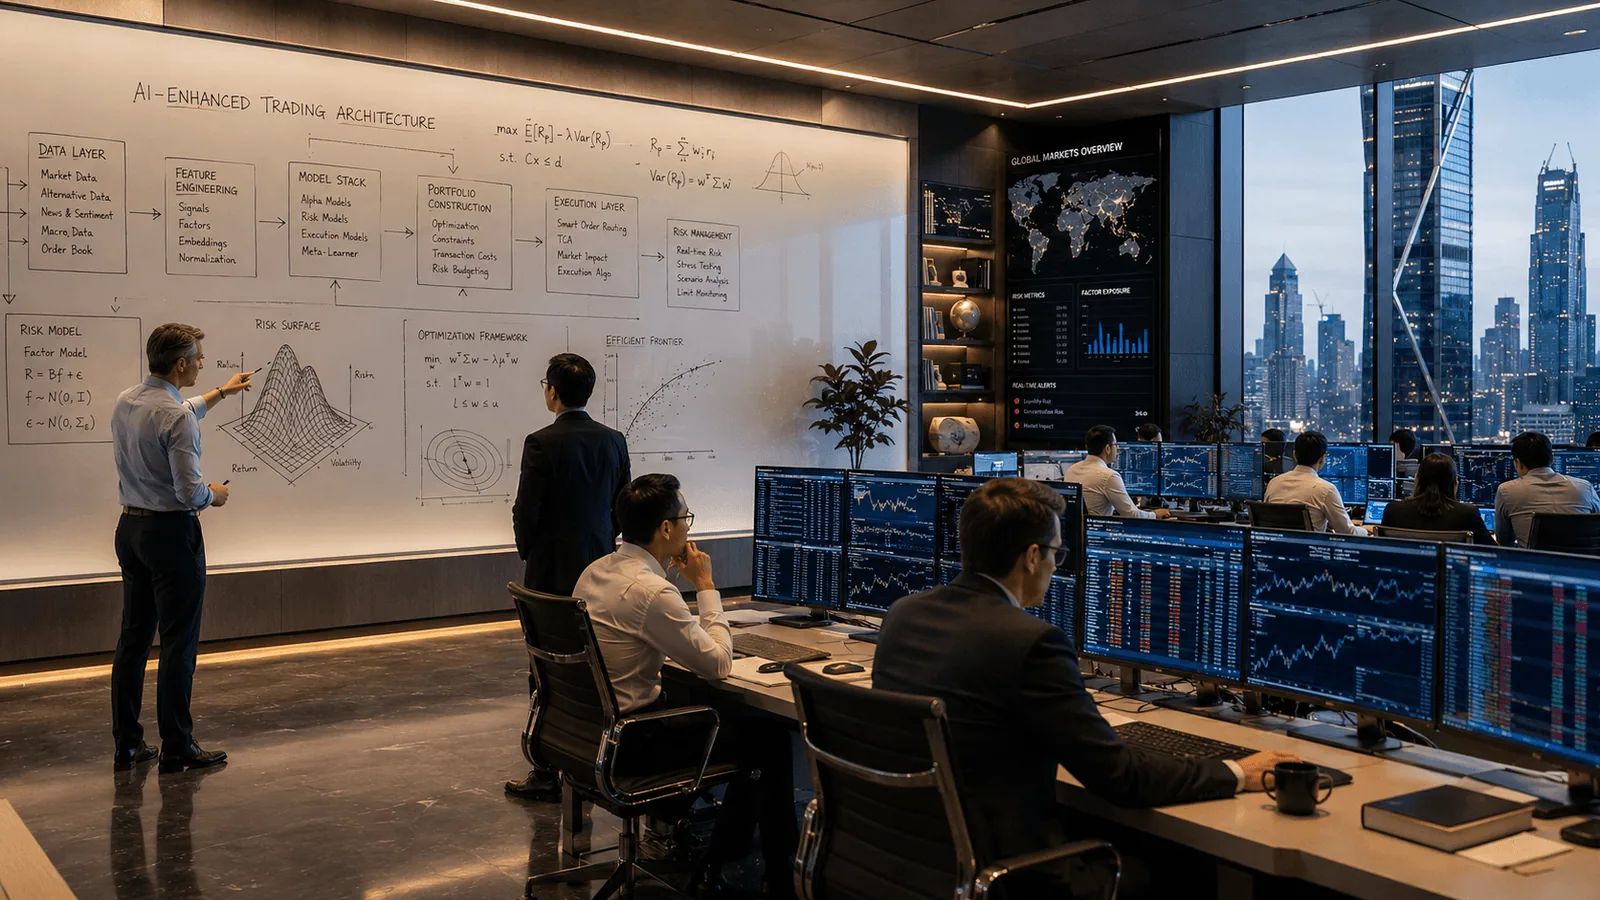
A “hedge fund in a box” is a bundled set of tools, services or software that gives a new manager the operating functions of a fund without building each one separately. It does not replace a manager's strategy, judgment or accountability, and it does not remove regulatory obligations.
The phrase is used loosely, so the useful question is not whether a product carries the label. It is which functions the bundle actually covers, which it leaves with the manager, and how you would check either claim.
- Define the box by functions, not branding: research, execution, risk, operations, compliance and reporting.
- A platform can replace repeated, rules-based work. It cannot replace work that rests on a named person or a legal status.
- Capital is a seventh question that the six functions do not answer.
- Treat every claim about cost, speed and capability as the vendor's own until you have tested it.
What does “hedge fund in a box” actually mean?
The term has been used for more than one kind of offering. What they share is a promise of compression: fewer vendors, fewer integrations and a shorter path from a strategy to an operating fund. What differs is the scope of the box.
Fund-formation services
Handle legal documents, administration and service providers so that a vehicle can be launched.
Software or hardware appliances
Package trading and reporting systems so that the manager does not integrate them one by one.
Platforms with capital access
Combine software with access to capital or distribution, so that the manager can be introduced to allocators.
Before comparing products, define the scope in terms of functions, not branding. Two products with the same label can cover entirely different parts of a fund.
Which functions must an emerging manager stand up?
Any systematic or discretionary manager, however it launches, has to cover six areas. A platform may cover some, all or none of them.
01. Research
Idea generation, data, testing, and a record of what was tried and rejected.
02. Execution
Order generation, routing to brokers, and reconciliation of positions, cash and weights.
03. Risk
Mandate, concentration, leverage, margin and drawdown limits, with owners and escalation paths.
04. Operations
Net asset value inputs, administration, custody and broker relationships, and the daily control cycle.
05. Compliance
The licensing or regulatory position, policies, record keeping and investor eligibility rules.
06. Reporting
Investor communications, evidence packs and the documents that support diligence.
What can a platform replace, and what can it not?
A platform can replace repeated, rules-based work and the cost of integrating separate vendors. It cannot replace the parts of a fund that rest on a named person or a legal status.
| Area | A platform can plausibly cover | The manager still owns |
|---|---|---|
| Research | Testing infrastructure, experiment records, data pipelines | The edge itself and the decision to trade it |
| Execution | Order routing, broker connectivity, reconciliation | Strategy definition and execution policy |
| Risk | Continuous limit monitoring, stress tests, exception alerts | Setting the limits and acting on breaches |
| Operations | Workflow, control checks, record keeping | Accountability for outcomes |
| Compliance | Tooling, templates, an existing regulatory umbrella where offered | Meeting obligations that apply to the manager personally |
| Reporting | Drafting, evidence assembly, document versioning | Approving what is sent and the accuracy of every figure |
| Capital | Introductions or a marketplace, where offered | Winning and keeping allocations |
The right column does not shrink with better software. If a vendor implies that it does, treat that as a finding in your diligence.
How should you evaluate any hedge-fund-in-a-box platform?
Use the same discipline you would apply to a manager. The eight tests below are ordered so that the cheapest to check come first.
- 01Scope in writing. Which of the six functions are covered, and which are explicitly excluded? Ask for the answer in a document, not a demo.
- 02Human control points. Where does a person approve, and where does software act alone? Outbound investor communications and limit overrides are the two to test first.
- 03Evidence trail. Can you see how a figure was produced, which version of a document was sent, and which ideas were rejected?
- 04Regulatory position. Does the platform operate under its own license or approval, and what exactly does that cover for you? Verify any approval on the regulator's own register, not on the vendor's page.
- 05Exit and portability. If you leave, what do you keep: data, records, code, broker relationships?
- 06Cost structure. Is pricing by fund, by assets, by seat or by revenue share? Obtain the figures from the contract, and compare them with what separate vendors would cost for the same scope.
- 07Source of every claim. Treat cost savings, speed and capability statements as the vendor's own until you have verified them.
- 08Dependency on the vendor's capital. If the box comes with allocations, understand the terms, lock-ups and fee sharing before you build on it.
Qlumina's 38-point forensic due diligence framework shows the evidence standard that allocators apply to managers, which is the standard a platform's output will eventually be read against.
What happens when something goes wrong?
A bundle concentrates risk in one provider, so the useful test is not how it behaves on a good day. Ask what the arrangement does under four stresses.
| Event | Question to settle in advance |
|---|---|
| The platform has an outage | Can the manager keep trading and reporting by other means, and who decides when to switch? |
| The vendor changes hands or closes | What do you keep, in what format, and how quickly can another provider take over the functions? |
| A regulator or auditor asks for a record | Can the full evidence trail be produced, including versions and approvals, without the vendor's help? |
| An allocator asks for the detail behind a figure | Can the manager show how the number was produced, from inputs to output, in their own words? |
How should an allocator read a manager that runs on a platform?
The same boxes appear in an allocator's diligence, from the other side. A manager running on a platform is not a weaker candidate for it, but the allocator should know which functions are bought in. Five questions cover most of it.
- 01Which functions run on a platform, and which are done by the manager's own staff?
- 02Where does the manager's accountability sit when software produces a figure or a document?
- 03Which regulatory approval does the manager operate under, and where can it be verified?
- 04What happens to the account if the platform relationship ends?
- 05Is the evidence in front of you from sources the platform and manager do not control?
How does the traditional launch compare?
The conventional path assembles each function from separate providers: offshore legal and structuring, a prime broker, independent directors and an audit, and execution and risk software. Our note on the emerging quant spin-out dilemma sets out the friction in that route and the alternative Qlumina describes, and the note on the Cayman master-feeder covers the fund structure it often ends in. The comparison below is structural, not a cost estimate.
| Dimension | Assemble separately | Bundled platform |
|---|---|---|
| Number of vendors | Many, each with its own onboarding | Fewer, with one scope to diligence |
| Integration burden | Manager carries it | Vendor carries it, within stated scope |
| Control over each component | High | Depends on the platform's design |
| Concentration risk | Spread across providers | Concentrated in one provider |
| Pricing | Quoted separately, obtained from each source | Single quote, obtained from the vendor |
Neither column is better in general. The right choice depends on the manager's team, strategy and need for control.
How does Alpha OS describe itself?
Alpha OS is Qlumina's platform for portfolio managers. On its own page it is described as a “hedge fund in a box” with every desk of the fund on one live screen. The page describes the following.
The portfolio managers page also describes a regulated umbrella: managers operate under Qlumina's BVI approved manager status from day one, with regulated partners used where a jurisdiction requires one. Admission to the Apex Marketplace is described as resting on three gates covering whether the edge is real, whether it can be run safely and whether it holds up live. See the programs and the marketplace pages for how those programs are presented.
Where do the other notes in this series fit?
Platform choice is one input to a wider launch decision. Related notes cover trade-only LPOA managed accounts, Swiss AMC exposure and CTA replication through an index, a fund or a managed account. The full library is on the insights index.
Frequently asked questions
What is a hedge fund in a box?
It is a bundled offering that covers some or all of the operating functions of a fund, such as research, execution, risk, operations, compliance and reporting. The scope varies by provider, so the label alone says little.
Does a hedge fund in a box remove the need for a regulatory license?
Not by itself. Whether a manager needs its own authorization depends on the jurisdiction and the activity, and some platforms operate under their own approval. Confirm the position with legal counsel and the regulator's register.
Can software replace the people in a fund?
Software can take over repeated, rules-based work, and some platforms describe human oversight at defined control points. Accountability for decisions, limits and investor communications remains with named people.
What should I ask a vendor first?
Ask for the scope in writing: which of the six functions are covered, which are excluded, and where a person must approve. Then ask how pricing is set and what you keep if you leave.
Is Alpha OS the same as an investment program?
No. Alpha OS is described as an operating platform for portfolio managers, while programs are strategies offered to professional investors in separate account format. They are presented on different pages of the Qlumina site.
Risk and eligibility
This note is educational only and is not an offer or solicitation. Materials are directed only to professional investors. Investing involves substantial risk of loss, and past performance is no guarantee of future results. Qlumina is a BVI FSC approved investment manager.
Alpha OS
See the Platform for Portfolio Managers
Systematic managers can read how Qlumina describes qualification, the platform and the regulated umbrella it operates under.
Research notes are published for professional readers. Not an offer or solicitation. Risk disclosure